SUPERMARKET INTELLIGENCE: Q3 2026 Market Dynamics & Procurement Trends
Supermarket procurement teams face mounting pressure from margin compression and shifting consumer demand for value-oriented fresh and private label offerings in the second half of 2026.
Market Overview
Supermarket chains across Southern Africa are navigating a complex Q3 landscape characterized by inflation stabilization, rising logistics costs, and intense competition from emerging discount formats. Procurement directors report increased focus on direct sourcing relationships with producers, particularly in fresh produce and protein categories, to protect margins.
Key Procurement Trends
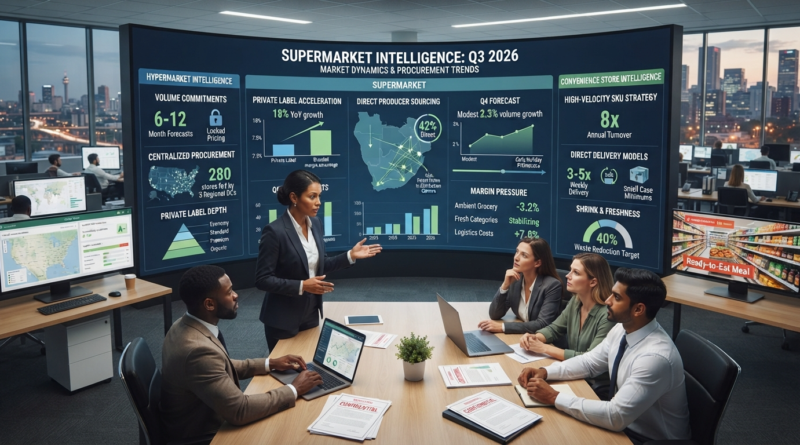
Private Label Acceleration Supermarket buyers are expanding private label portfolios at twice the rate of previous years, with fresh ready-to-eat meals and plant-based proteins showing the strongest growth. This shift reflects both consumer price sensitivity and improved margins for retailers (typically 15-25% higher than branded equivalents).
Direct Producer Relationships Large supermarket chains are bypassing traditional distributors for 30-40% of fresh produce, establishing direct contracts with farmers and cooperatives. This reduces cost volatility and improves shelf stability but requires enhanced supply chain coordination.
Sustainability Compliance Pressure Procurement teams report increasing supplier audits around water usage, carbon footprint, and packaging waste. Suppliers lacking sustainability certifications face shelf space reduction or delisting within 12-18 months.
SKU Rationalization Average supermarket produce sections have contracted by 8-12% SKUs, while ambient grocery sections show consolidation around top-20 brands by category. Procurement is optimizing for inventory turnover and floor space ROI.
Pricing & Margin Environment
- Ambient grocery: 2-4% margin compression expected through Q4
- Fresh categories: Stabilizing prices with seasonal volatility
- Private label: Growing 12-18% YoY with 5-8% margin advantage over branded
- Logistics costs: Up 6-9% despite fuel price stabilization; last-mile delivery remains a pain point
Buyer Behavior Shifts
Supermarket procurement is increasingly data-driven, with 65%+ of chains deploying AI-powered demand forecasting. This creates opportunities for agile suppliers who can respond to short-cycle orders and reduce forecasting errors.
Bulk purchase cycles are compressing—buyers prefer smaller, more frequent orders to minimize inventory holding costs, particularly for fast-moving categories.
Supply Chain Priorities
- Traceability & Cold Chain Integrity — Technology investment in real-time tracking
- Lead Time Optimization — Reducing order-to-shelf cycles from 21 days to 14 days
- Waste Reduction — Targeting 40% reduction in shrink across fresh categories
- Supplier Segmentation — Consolidation around A-tier strategic partners
Forecast: Q4 2026
Supermarket procurement teams expect modest volume growth (2-3%) driven by seasonal gifting and holiday demand, but price realization will remain under pressure. Early holiday promotions (August-September) will set tone for margin environment through year-end.
Frequently Asked Questions
Q: What’s the typical reorder cycle for supermarket produce buyers? A: Traditional weekly or bi-weekly orders remain standard, but larger chains are testing 3-times-per-week micro-fulfillment models to reduce waste and improve freshness. Smaller format stores remain on weekly cycles.
Q: How much does sustainability certification impact shelf space negotiations? A: Increasingly critical. Chains report sustainability as a non-negotiable requirement for new listings or expanded facings. Suppliers without certifications may lose 15-30% shelf space over 18 months.
Q: Which categories offer the best margin protection for supermarket buyers? A: Plant-based proteins, organic ranges, and ready-to-eat meals are protecting margins. Commodity fresh (potatoes, onions, basic proteins) remain highly competitive with slim margins.
Q: Are supermarkets consolidating suppliers or diversifying? A: Mixed approach—consolidation around top-tier suppliers for volume, but diversification for specialty and premium categories to differentiate shelf sets. Average procurement team now manages 40-60% fewer active suppliers than 2 years ago.
Sources & Industry Data
- Grocery Retail Association Q3 2026 Procurement Survey
- Supply Chain Analytics Council — Supermarket Buyer Pulse
- National Agricultural Bureau — Fresh Produce Market Intelligence
- Retail Technology Commission — Demand Forecasting Study