HYPERMARKET INTELLIGENCE: Volume Commitments & Channel Strategy Update
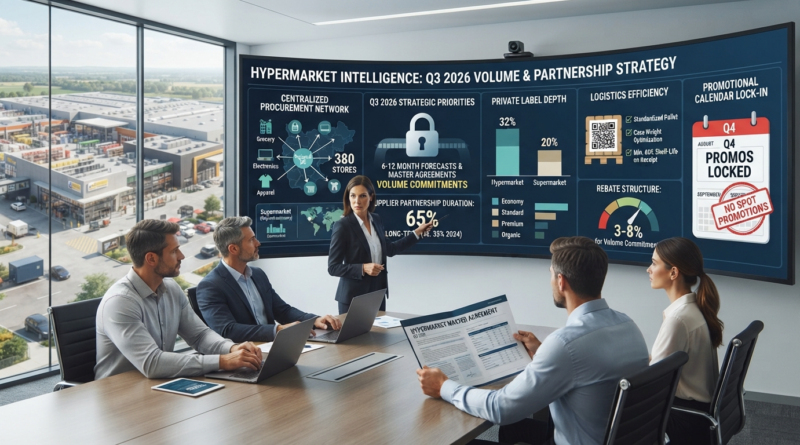
Hypermarket procurement teams are prioritizing volume commitments and long-term supplier partnerships as they compete with e-commerce and discount retailers, requiring suppliers to lock in 6-12 month forecasts.
Market Overview
Hypermarkets represent a distinct procurement strategy compared to supermarkets, characterized by higher volume thresholds, deeper category penetration, and more sophisticated logistics infrastructure. Q3 2026 sees hypermarket chains refining their grocery-electronics-apparel integration, with procurement implications across all divisions.
Procurement Model Distinctions
Volume-Centric Buying Hypermarkets operate on volume-based economics, requiring suppliers to commit to minimum quarterly forecasts (typically 30-50% higher than supermarket equivalents). This creates both opportunity and risk for suppliers managing demand volatility.
Centralized Procurement Unlike supermarkets with regional buyer autonomy, hypermarket procurement is highly centralized. A single buyer decision affects 50-300+ store network, reducing negotiation complexity but raising stakes on execution.
Integrated Category Management Hypermarket buyers manage across grocery, household, health & beauty, and increasingly electronics. Cross-category bundling and promotional strategies create opportunities for suppliers offering multiple SKUs.
Strategic Buying Priorities
Long-Term Partnerships Hypermarket procurement teams prefer 6-12 month master agreements with quarterly volume reviews over transactional purchase orders. This reduces admin overhead and improves forecasting reliability.
Private Label Depth Hypermarket private label penetration in grocery is 25-35% (vs. 18-22% in supermarkets), with larger breadth across price tiers (economy, standard, premium). This requires suppliers to manage multiple production runs or co-packing arrangements.
Logistics Efficiency Hypermarkets demand centralized distribution through regional warehouses, not store-direct delivery. Suppliers must optimize case weights and pallet configurations to match hub requirements.
Promotional Calendar Lock-In Hypermarket promotions are planned 8-12 weeks in advance with locked supplier pricing. Spot promotions are rare; advance planning is non-negotiable.
Margin & Volume Economics
- Average order size: 40-60% larger than supermarket equivalents
- Promotional support: 2-4% of net sales typically required from suppliers
- Payment terms: 30-45 days (vs. 14-30 for supermarkets)
- Volume rebates: 3-8% for hitting quarterly commitments; clawback penalties for misses
Category Opportunities
High-Growth Segments:
- Organic ranges (8-12% YoY growth in hypermarkets vs. 4-6% in supermarkets)
- Health-focused snacking (protein bars, functional beverages)
- Ethnic/regional specialties (expanding from single-shelf to full-section allocations)
Competitive Pressure:
- Ambient grocery (increasingly SKU-rationalized)
- Basic commodities (private label dominance, 70%+ in some categories)
Supply Chain Requirements
Hypermarket logistics expectations:
- Lead times: 10-14 days from order to warehouse receipt
- Case pack minimums: Typically 50-100 cases per SKU
- Pallet configurations: Standardized 1200x1000mm, mixed-SKU pallets supported
- Shelf-life requirements: Minimum 60% remaining shelf-life on receipt
Frequently Asked Questions
Q: Can suppliers negotiate short promotional cycles with hypermarket buyers? A: Rarely. Hypermarket promotional calendars are locked 8-12 weeks out. Emergency/spot promotions require executive escalation and are typically only granted for new product launches or crisis situations.
Q: What volume commitment do hypermarkets typically expect? A: Minimum quarterly forecasts range from 30-100% higher than supermarket quantities. Buyers expect 85%+ forecast accuracy; misses trigger rebate clawbacks or delisting.
Q: How do hypermarkets differ from supermarkets on private label strategy? A: Hypermarkets maintain 3-4 private label tiers (economy, standard, premium, organic) vs. supermarkets’ typical 1-2 tiers. This requires suppliers to support multiple quality/price points simultaneously.
Q: Are hypermarket payment terms negotiable? A: Less so than supermarkets. Standard 30-45 day terms are firm; early-payment discounts (2-3%) may be available for cash flow-constrained suppliers, but extended terms are rarely granted.
Q: What’s the typical lifecycle for a new product launch in hypermarkets? A: 6-month trial with minimum shelf space allocation (5-8 facings in 30-50 stores) followed by performance review. Success metrics: 2-3% market share capture within category, sell-through velocity matching category average.
Sources & Industry Data
- Hypermarket Association Regional Procurement Framework
- Logistics Council — DC Efficiency & Case Pack Optimization Study
- Category Management Institute — Private Label Strategy Report
- Supply Chain Consortium — Forecast Accuracy & Rebate Analysis